
 XM
 Bybit
 Binance
 Robinhood
 Webull
 IC Markets
 Pepperstone
 OKX
 Vantage
 VT Markets
 BingX
 Gate.io
 Kucoin
 MEXC
 Exness
 Bitget

Choosing where to start a loan search matters just as much as the loan itself, and this Paisa247 review takes a close, balanced look at one of India’s newer digital loan-comparison platforms. Paisa247 is not a lender. Instead, it acts as an online marketplace that lets you fill in one short application and receive personalized offers from a network of RBI-registered NBFCs and banks, so you can compare interest rates, EMIs, and tenures side by side before you commit. The service is free for borrowers, fully digital, and covers everything from small-ticket app loans of a few thousand rupees up to personal loans of several lakhs. This guide breaks down who runs the platform, how it actually works, the loan options and real costs involved, what its user feedback looks like, and the important points every borrower should weigh before applying at the official Paisa247 website.
What Is Paisa247 and How Does It Work?
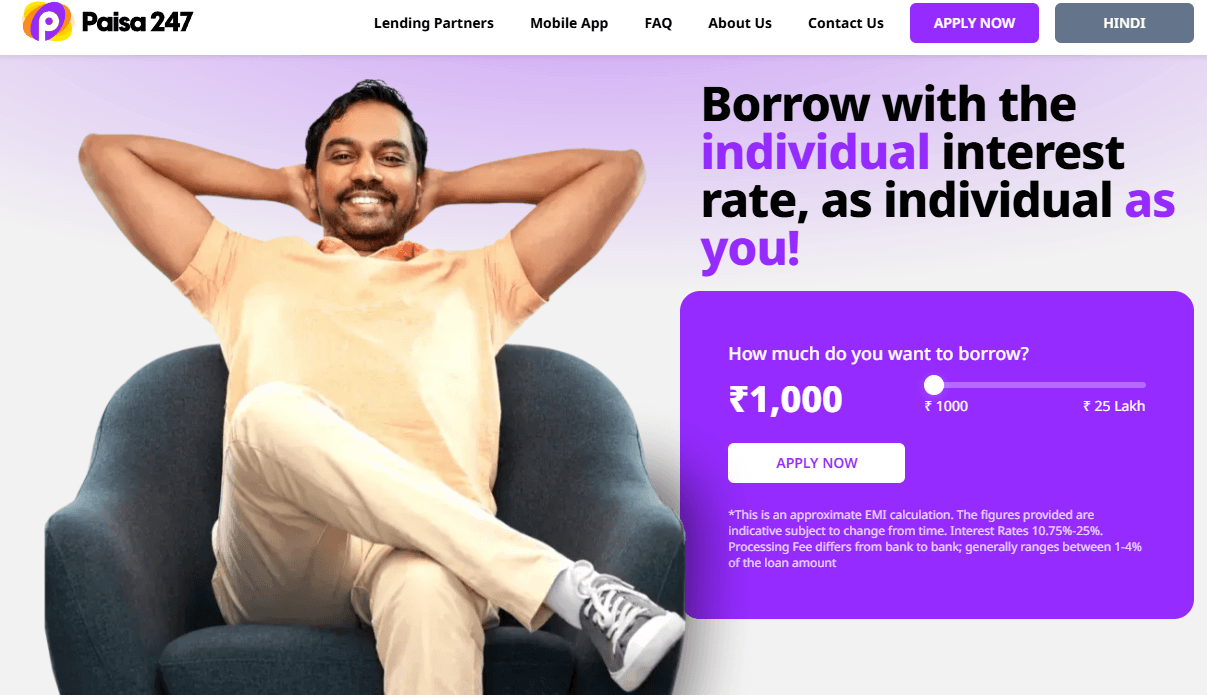
To make sense of this Paisa247 review, it helps to be clear about what Paisa247 is and, just as importantly, what it is not. Paisa247 is a loan-comparison and facilitation platform built specifically for the Indian market. It does not issue loans from its own balance sheet and does not make credit decisions. Instead, it matches borrowers with third-party lenders and passes the application along; the actual loan, the final approval, the interest rate, and the collection are all handled by the lending partner.
The platform is operated by RIGA MARKETPLACE PAISA247, a company registered in Maharashtra in 2024 (CIN U66190MH2024FTC430669) and headquartered at a WeWork facility in Goregaon East, Mumbai. Its corporate identity number is classified as a subsidiary of a foreign company, which is consistent with its roots: Paisa247 is the India-facing brand of the Jeff App group, a Riga, Latvia–based financial-marketplace operator founded around 2019–2020 that runs similar data-driven loan marketplaces across emerging markets such as Vietnam, the Philippines, Indonesia, and Mexico. Jeff publicly raised seed funding in 2024 specifically to expand into India, and Paisa247 is the result of that push. This means the platform is a very young entrant in India, even though the group behind it has several years of experience running comparison marketplaces elsewhere.
A typical journey with Paisa247 is designed to be simple and paperless, moving through a few clear stages.
- Enter Your Details: Fill in one short online form with your basic information and the loan amount you are looking for. More complete information leads to more accurate matches.
- Compare Offers: The platform returns personalized loan options from its network of lending partners, so you can compare interest rates, EMIs, tenures, and eligibility in one place.
- Choose a Lender: Select the offer that best fits your needs and continue the application directly with that lender through the Paisa247 app or website.
- Complete Verification: The chosen lender carries out its own KYC, credit check, and approval process according to RBI rules.
- Receive Disbursal: Once the lender approves, funds are transferred directly to your bank account, often within a day or two depending on the partner.
Each step reflects the platform’s core promise: doing the comparison legwork for you rather than making you apply to lenders one at a time.
Why Do Borrowers Choose Paisa247?
The Indian loan-comparison space is competitive, so it is worth examining what draws borrowers to Paisa247 in this review. Several features consistently attract sign-ups, particularly among first-time and app-savvy borrowers who value speed and convenience.
The most commonly cited reasons borrowers use Paisa247 include the following:
- One Application, Many Offers: A single form generates personalized offers from a wide list of lenders, saving you from applying to each one separately.
- Free for Borrowers: Paisa247 does not charge any service fee for using the comparison platform; its revenue comes from the lending partners, not from you.
- Wide Lender Network: The platform lists 30-plus NBFCs and banks, from well-known names to smaller app-based lenders, giving a broad spread of loan sizes and profiles.
- Fully Digital Process: The application is paperless and can be completed from a phone, with fast disbursal advertised once a lender approves.
- Range of Credit Profiles: Because it works with many lenders, the platform can surface options for salaried and self-employed applicants, and some partners cater to thinner credit files.
On paper, these advantages make Paisa247 a convenient starting point, especially for borrowers who want to weigh several offers quickly instead of committing to the first lender they find.
What Loan Options and Amounts Does Paisa247 Offer?
A central part of any Paisa247 review is understanding the range of loans available through the platform. Because Paisa247 is an aggregator rather than a single lender, the loan amounts, rates, and tenures depend entirely on the partner you ultimately borrow from. Broadly, loan amounts run from as little as ₹1,000 for small-ticket app loans up to around ₹25 lakh with larger NBFC and bank partners, and some partners advertise higher ceilings for well-qualified applicants. Repayment tenures range from a few months on short-term app loans to as long as five years (up to roughly 60 months) on larger personal loans.
How Do Paisa247’s Loan Options Compare?
The offers differ mainly in ticket size, tenure, and the type of borrower they suit. The table below summarizes the broad categories you are likely to see on the platform:
| Loan Type | Typical Range & Key Traits | Best Suited For |
|---|---|---|
| Small-Ticket App Loans | Roughly ₹1,000 to ₹50,000, short tenures, fast approval, minimal documentation, higher effective APR | Urgent small needs, first-time or thin-file borrowers who accept higher costs |
| Mid-Size Personal Loans | Roughly ₹50,000 to ₹5 lakh, tenures up to a few years, salaried-friendly, moderate rates for good credit | Salaried borrowers with a decent CIBIL score consolidating or funding planned expenses |
| Larger Personal Loans | Up to around ₹25 lakh with select bank/NBFC partners, longer tenures up to about 60 months, lowest rates for strong profiles | Well-qualified borrowers with higher income and strong credit history |
| Line of Credit / Flexi Loans | Approved limit you draw from as needed, interest charged only on the amount used, offered by certain partners | Borrowers with irregular or recurring short-term cash needs |
Each category balances speed, cost, and size differently, so the right choice depends on your income, credit score, and how quickly you need the funds. Because the final terms come from the lender and not from Paisa247, two identical-looking offers can carry very different real costs once fees are included.
What Are Paisa247’s Terms and Features?
Beyond the loan categories, this Paisa247 review looks at the terms and conditions that actually affect what you pay. Since Paisa247 is a matchmaking layer, these figures are ranges set by its partners rather than fixed rates the platform controls.
The most notable terms and features include the following:
- Interest Rates and APR: Headline interest rates are commonly quoted from around 10.75%, and the platform’s own disclosures state a minimum APR near 9.99% p.a. that can rise to roughly 44% p.a. on higher-risk, short-term products. Some app-store listings cite starting rates around 11.99% with a maximum APR near 36% for certain partners. Your actual APR is set by the lender based on your credit profile.
- Processing Fees: Lenders typically charge a processing fee of around 1% to 4% of the loan amount, plus 18% GST on that fee. These costs are deducted or added on top and materially raise the true cost of borrowing.
- Repayment Tenure: Ranges from short terms of a couple of months on small app loans to as long as five years on larger personal loans, depending on the partner.
- Eligibility: Typical criteria across partners include being an Indian resident, aged roughly 21 to 60, with a minimum monthly income near ₹15,000 and, for mainstream offers, a CIBIL score around 650 or higher. Requirements vary by lender, and some partners consider lower scores.
- Lending Partners: The network includes 30-plus RBI-registered NBFCs and banks such as CASHe (Bhanix Finance), Money View, Aditya Birla Capital, InCred Finance, Branch, mPokket, Zype, NIRA, and others, all of which the platform states comply with RBI Digital Lending Guidelines.
As a concrete illustration, the platform’s own representative example describes borrowing ₹1,00,000 at 13% over 12 months: a 2% processing fee (₹2,000) plus 18% GST (₹360) brings total fees to ₹2,360, with a monthly EMI of about ₹8,932, total interest of roughly ₹7,181, and total repayment near ₹1,10,129. This is a useful reminder that the interest rate alone never tells the full story; fees and GST are part of the real cost.
What Are the Pros and Cons of Paisa247?
A balanced Paisa247 review must weigh convenience against the limitations of any aggregator model. The platform can genuinely save time, but there are real trade-offs that borrowers should understand before applying.
The main advantages reported by users include:
- Time-Saving Comparison: One application surfaces multiple offers, removing the need to fill out separate forms with each lender.
- No Cost to Use: The comparison service itself is free for borrowers, with no service or subscription charge.
- Broad, RBI-Aligned Network: A wide range of RBI-registered NBFC and bank partners, spanning small app loans to larger personal loans, all stated to follow RBI digital-lending rules.
- Fast, Fully Digital Experience: A paperless process with quick disbursal once a partner approves, plus a mobile app and step-by-step guidance.
At the same time, several important limitations are worth noting:
- Not a Lender and No Control Over Final Terms: Paisa247 only facilitates matches. It does not set your rate, approve your loan, or handle repayment, so the borrower must still read and accept each lender’s terms separately.
- Costs Can Be High on Some Partners: With APRs reaching up to roughly 44% p.a. and processing fees plus GST on top, short-term products from some partners can be expensive; the headline “from 9.99%” rate applies only to the strongest profiles.
- Very New in India With Limited Independent Reviews: The Indian entity was registered in 2024, and independent third-party reviews are still thin, so there is a short public track record to judge against.
- Data and Privacy Considerations: The Jeff group’s model relies on collecting and analyzing alternative data such as device metadata and behavioral signals for matching and fraud checks, so privacy-conscious users should read the privacy policy and app permissions carefully.
Considering both sides allows borrowers to use Paisa247 for what it does well — quick comparison — while staying clear-eyed that the responsibility for choosing a fair, affordable loan still rests with the borrower and the chosen lender.
What Do Real Paisa247 Reviews Say?
Public sentiment is a useful part of this Paisa247 review, though it should be read with the platform’s youth in mind. On its own website, Paisa247 features several positive customer testimonials praising a smooth, quick process and helpful support, with borrowers describing funds arriving within a day or two of applying. These on-site testimonials are, by nature, curated and not independently verified, so they are best treated as marketing rather than neutral feedback.
The platform also maintains apps on both Google Play and the Apple App Store, where it presents itself as a comparison service partnering only with RBI-registered lenders and lists representative loan examples and eligibility criteria. Some aggregator-style review sites echo the platform’s stated strengths — a single quick form, side-by-side comparison, no service fees, and access to dozens of personalized offers — while also flagging the obvious structural point that Paisa247 is only a comparison service, meaning users must apply and qualify separately with each lender and have no direct control over final loan terms.
In fairness, this Paisa247 review should acknowledge that the group behind the platform, Jeff App, has an established multi-year record running similar marketplaces in other emerging markets and has attracted recognition and venture funding for that model. What is still missing is a large body of independent, verifiable borrower reviews specific to the India operation, simply because it launched recently. Until that history builds up, the safest approach is to weigh the convenience of comparison against your own careful reading of each lender’s actual offer.
Who Is Paisa247 Best Suited For?
Bringing this Paisa247 review together, the platform tends to suit borrowers who want to shop around efficiently rather than commit to a single lender blindly. Those who might benefit most are salaried or self-employed applicants with a reasonable CIBIL score who are comfortable with a fully digital process and want to compare several offers before choosing. It can also help first-time borrowers see the range of what is available, provided they read the fine print. Borrowers who prefer a long-standing relationship with one bank, who want a human branch to walk them through the process, or who will not take the time to compare each lender’s APR and fees carefully may find a direct application to their own bank a better fit.
What Should First-Time Borrowers Keep in Mind?
Newer borrowers should approach any loan, and any aggregator, with care. Remember that Paisa247 does not lend or approve anything itself, so the real agreement is always with the partner lender. Before signing, look at the full APR rather than just the headline interest rate, since processing fees and 18% GST meaningfully raise the true cost. Confirm the lender is an RBI-registered NBFC or bank, read the Key Facts Statement (KFS) that Indian rules require before you agree, and check for prepayment charges, late fees, and the exact tenure. Above all, borrow only what you can comfortably repay from your monthly income, and treat any loan as a commitment with real consequences for your credit score if you fall behind.
What Is Finance-solutes.com and How Does It Support Borrower Knowledge?
Finance-solutes.com is a dedicated platform focused on financial education, lending insights, and emerging digital trends. For readers researching a Paisa247 review or any other financial service, the site offers clear, research-driven content designed to help both first-time and experienced borrowers make confident decisions.
The platform stands out for several reasons:
- Research-Based Content: Articles are built on careful research and real-world relevance.
- Beginner-Friendly Explanations: Complex lending and finance topics are broken down into accessible language.
- Up-to-Date Coverage: Content reflects current trends across lending, fintech, and personal finance.
- User-Focused Approach: Guides are written to answer the questions borrowers actually ask.
This makes Finance-solutes.com a useful starting point for anyone exploring loan platforms and modern financial tools.
 Start your loan comparison here: https://go.goodaff.eu/paisa247.in/utwellqs0r
Conclusion
This Paisa247 review reveals a convenient, free-to-use loan-comparison platform that can genuinely save borrowers time in a crowded Indian lending market. By letting you fill in one application and compare personalized offers from 30-plus RBI-registered NBFCs and banks, Paisa247 lowers the effort of shopping around, and it is backed by the Jeff App group’s multi-year experience running similar marketplaces across emerging economies. At the same time, the platform is only a facilitator: it does not lend, approve, or control your final terms, the Indian operation is very new with limited independent reviews, some partner products carry APRs up to roughly 44% p.a. plus fees and GST, and its data-driven model deserves a careful read of the privacy policy. For borrowers who value comparison and are prepared to scrutinize each lender’s KFS and true cost, Paisa247 is a reasonable place to start — as long as you borrow responsibly and confirm every figure before you sign.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or borrowing advice. Paisa247 is a loan-comparison and facilitation platform, not a lender; all loans, approvals, rates, and terms are provided by third-party RBI-registered NBFCs or banks. Interest rates, APRs, fees, and eligibility vary by lender and by borrower profile and can change over time. Borrowing carries real financial risk, including impact on your credit score if you fail to repay. Always review the lender’s current terms and Key Facts Statement, do your own research, and consider your own circumstances before applying.
Related Search: Paisa247 review, Paisa247 India, Paisa247 loan app, is Paisa247 safe, is Paisa247 legit, Paisa247 interest rate, Paisa247 personal loan, Paisa247 lending partners, loan comparison India, best loan aggregator India 2026, Paisa247 vs Paisabazaar, RBI registered NBFC loan app
Read More:
- CreditKasa UA Review: Fast Online Loans for Every Ukrainian
- AlexCredit UA Review: Quick Credit for Everyone in Ukraine
- Paisa247 Review: India’s Digital Loan-Comparison Platform
Finance Solutes
- Mail: contact@finance-solutes.com
- Website: https://finance-solutes.com/
- Hotline: +84 77 90 50 998 ( Whatsapp )
- Address: St. 6, Hung Vuong 2, Tan Hung W, D.7, HCMC
- t.me/finance_solutes
- Website: https://finance-solutes.com
- Hotline: +1 929 5636 439 ( Hotline )
- 26 Broadway, Suite 934, New York, 10004, US
